Grain Snippet: Harvest Delays Lift Lentils Despite Heavy Stocks
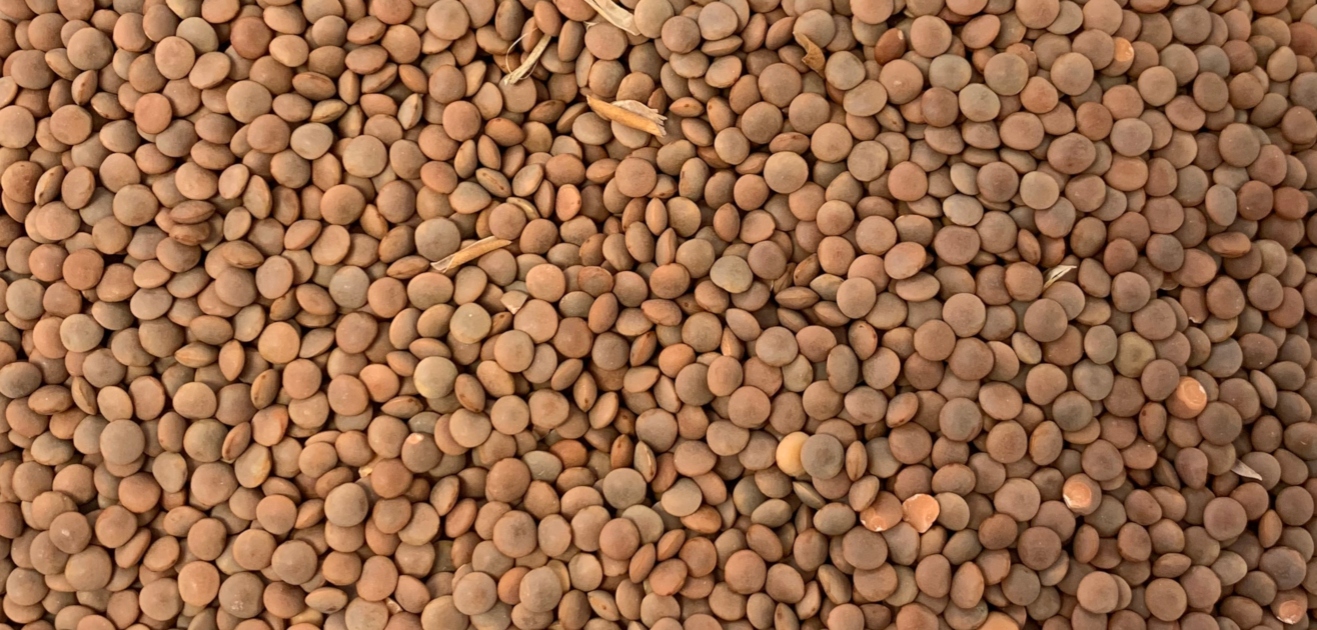
Lentil prices have firmed in recent weeks as a combination of shipping shorts, harvest delays and a declining Aussie dollar. Even as sites get filled to the brim with lentil, exporters in SA are seeking grain for nearby commitments. The price improvement reflects the reflects immediate delivery requirements whilst broadly remaining pressured (relative to prior season prices) amid a backdrop of substantial forecast supply. At the time of writing, prices at major delivery ports and packing sites sit between $590-$600/MT.
The stop-start harvest in South Australia has restricted deliveries ahead of mid-November vessel commitments. Limited container availability and packing capacity have also constrained alternatives, with some exporters beginning to shift demand past Nov/Dec and into the new year where container availability is expected to improve.
CloudBreak’s production estimate for Australia remains 2.50–2.74 MMT. Adding estimated carry-in stocks of approximately 420,000 MT would leave total supply around 2.9–3.2 MMT, compared with roughly 2.1 MMT last season. Some early yields have disappointed relative to grower expectations from earlier in the year, but the results remain too limited to establish a national trend.
With the rain and harvest delays comes another issue this harvest, in the form of poorer quality. Early South Australian deliveries have included reports of Ascochyta, colour defects and elevated weed seed counts. The proportion meeting export specifications will influence blending requirements, grade discounts and demand for clean grain.
Canada’s smaller harvest offers only partial relief from export competition. Agriculture and Agri-Food Canada’s October outlook estimates 26/27 production at 2.47 MMT, down approximately 27% from last year. Large opening stocks leave total supply just 4% lower, at 3.83 MMT. Much of the production decline was in green lentils, limiting the benefit for the red lentil market.
India’s Rabi season planting progress has picked up pace over the last week, but total pulse sowing remains around 14% behind this time last year, with chickpeas accounting for most of the shortfall. The monsoon season this year was belated in many regions and saw in a 13% rainfall deficit across India nationally, resulting in a later start to Rabi planting and lower anticipated yields for pulses. The pulse market is already reacting to the poor pigeon pea crop and lower forecasts chickpea yields. Higher pigeon pea and chickpea prices in India may encourage some substitution towards lentils, although differences in consumption and processing limit that response.
The market therefore remains sensitive to harvest progress, export quality and the timing of vessel demand. Due to lower domestic production, India is forecast to have another year of healthy pulse imports which will likely lend some support for the broader lentil market. However, substantial Australian and Canadian supplies continue to limit the scope for a sustained recovery.
This is a sample only, if you would like to view the entire document and our recommendations, please contact CloudBreak to discuss becoming a member on (08) 8388 8084.